Ask the Right Questions
Whether you’re dealing with a bank, credit union, or online lender, ask:
- What is the interest rate?
- How often is the interest compounded?
- If I miss a payment, will the rate increase?
- How much is the down payment?
- What are the loan’s repayment terms?
Gather Your Information
Before approaching a lender, have the following ready:
- Your credit score or FICO score from a credit reporting agency
- A W-2 or recent pay stub
- Government ID and proof of residence (driver’s license, utility bill, etc.)
Lenders use this information to verify your employment, address, and credit, and to determine whether you can get preapproved.
How to Compare Auto Loans
Once you have offers in hand, compare them on more than just the advertised rate. Look at:
- APR — the interest rate plus fees, which gives a fuller picture of the loan’s real cost
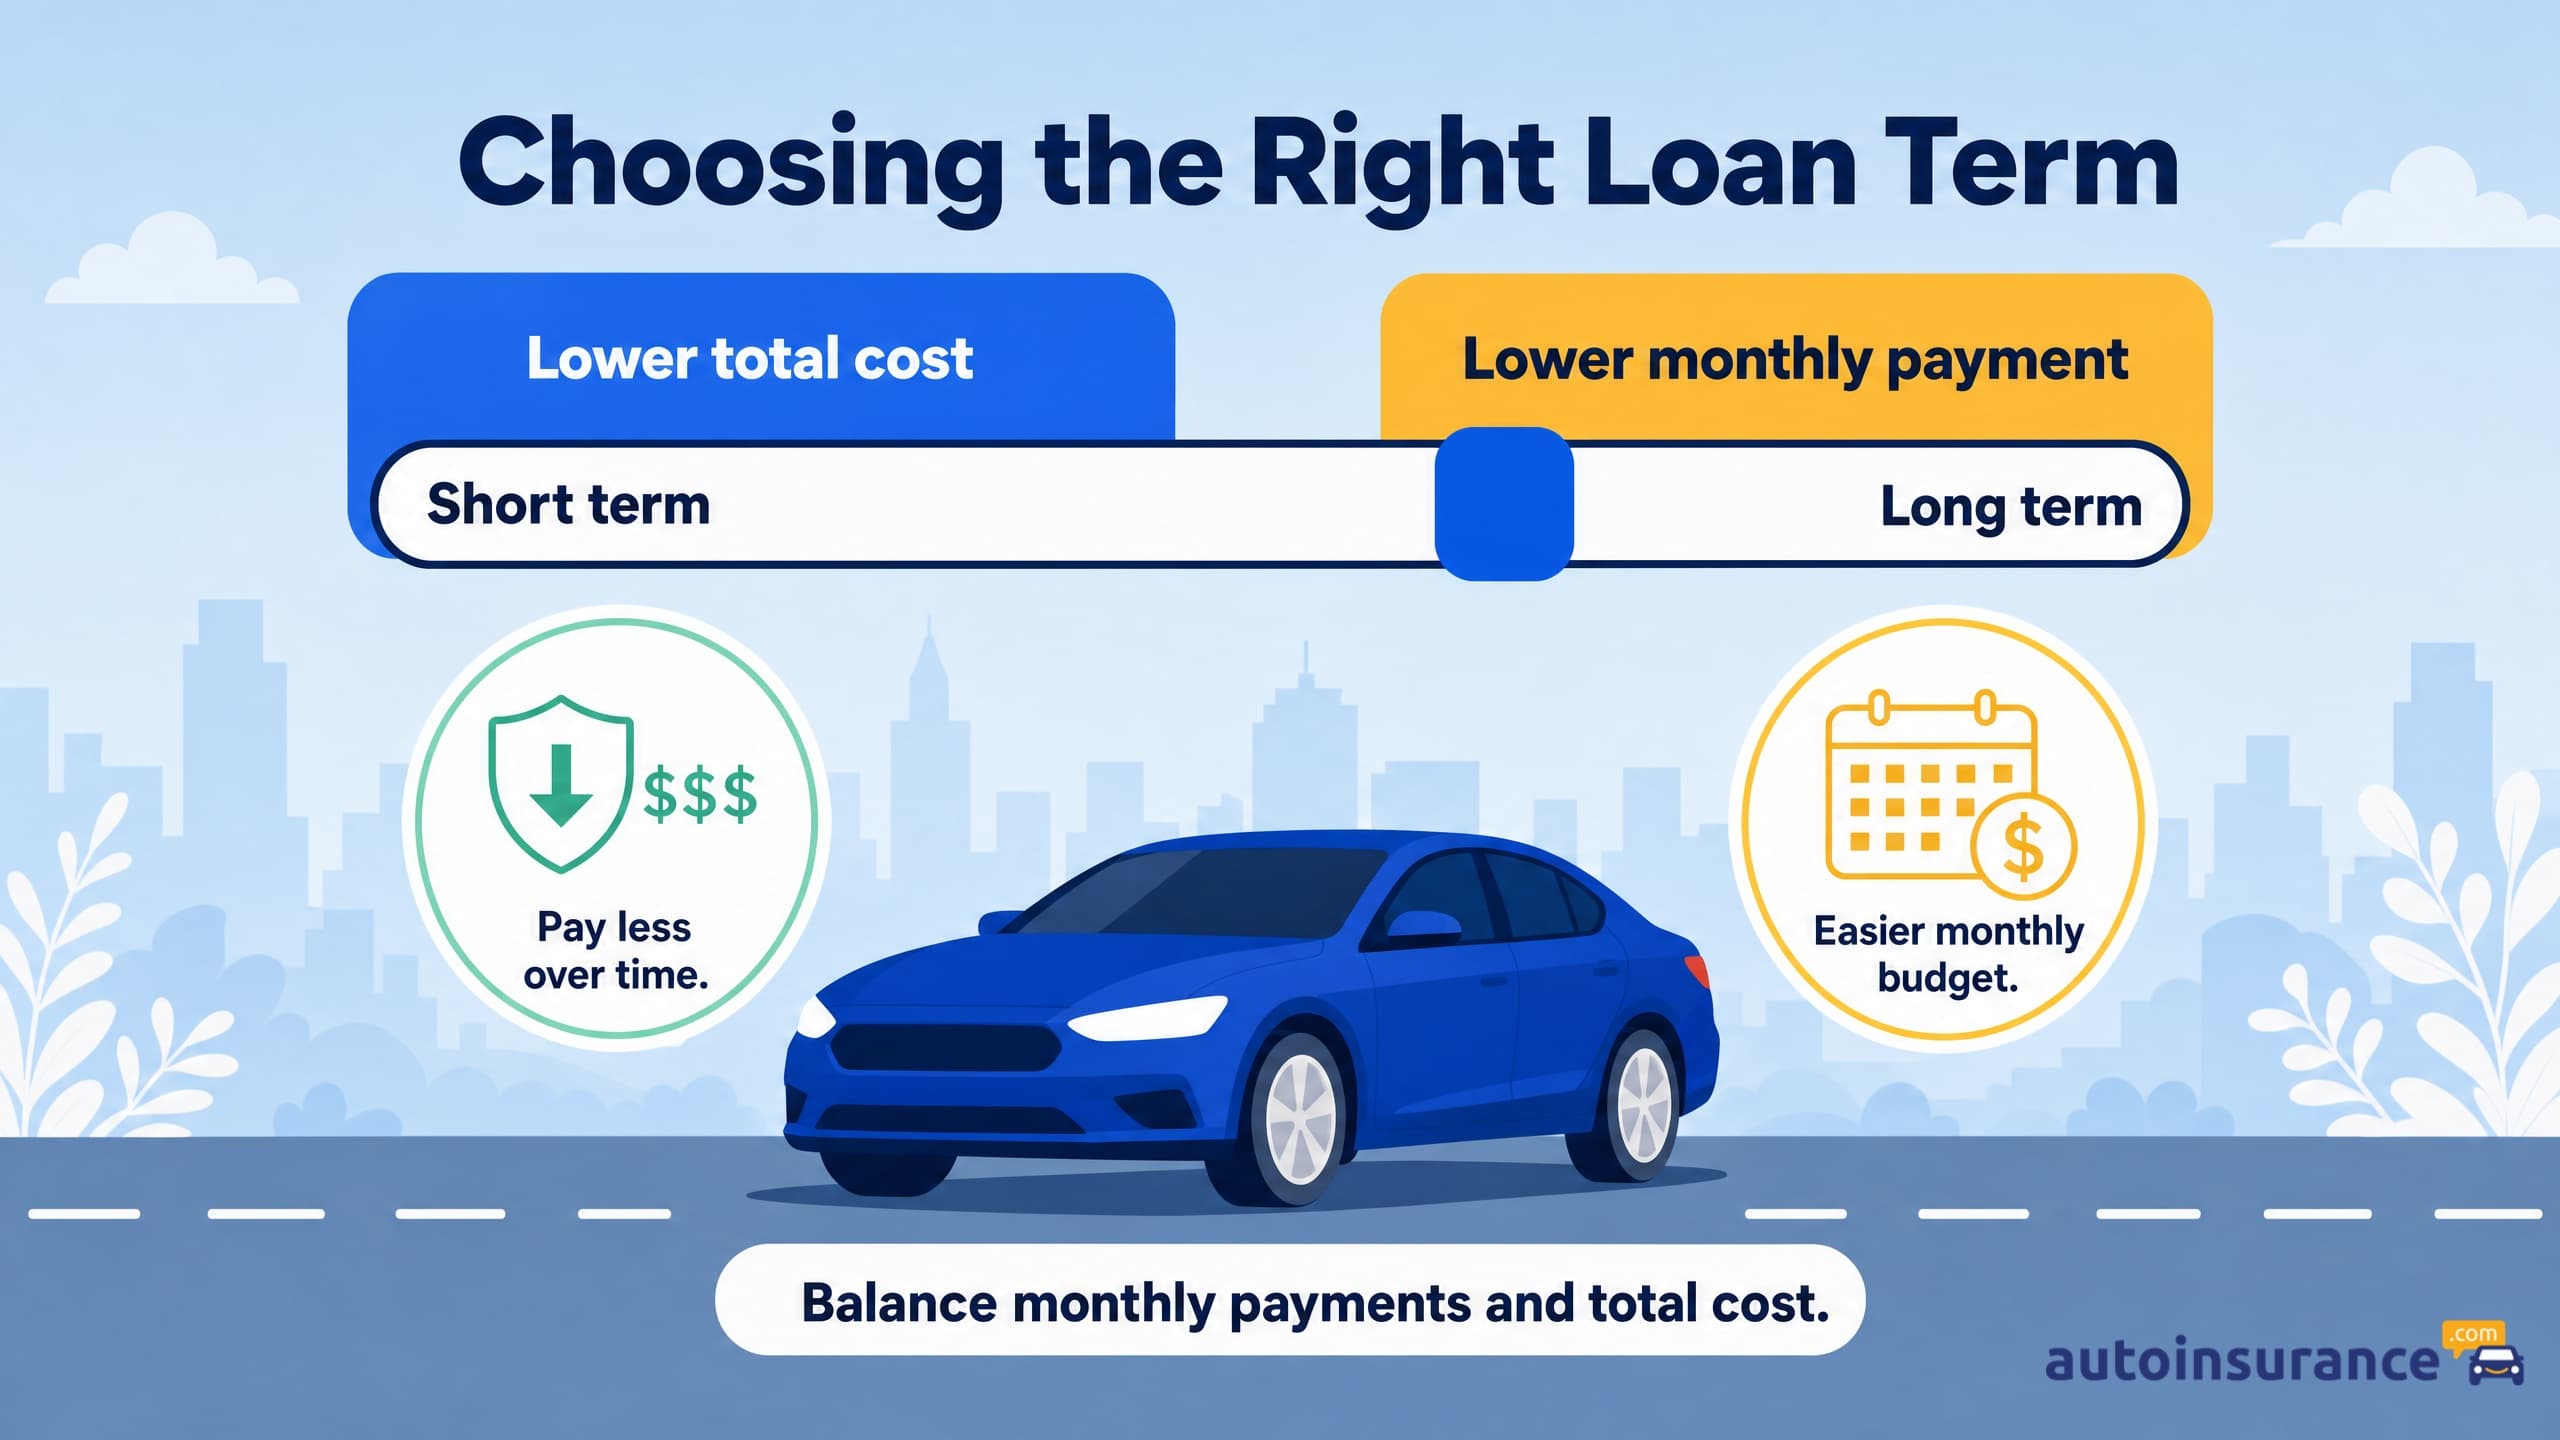
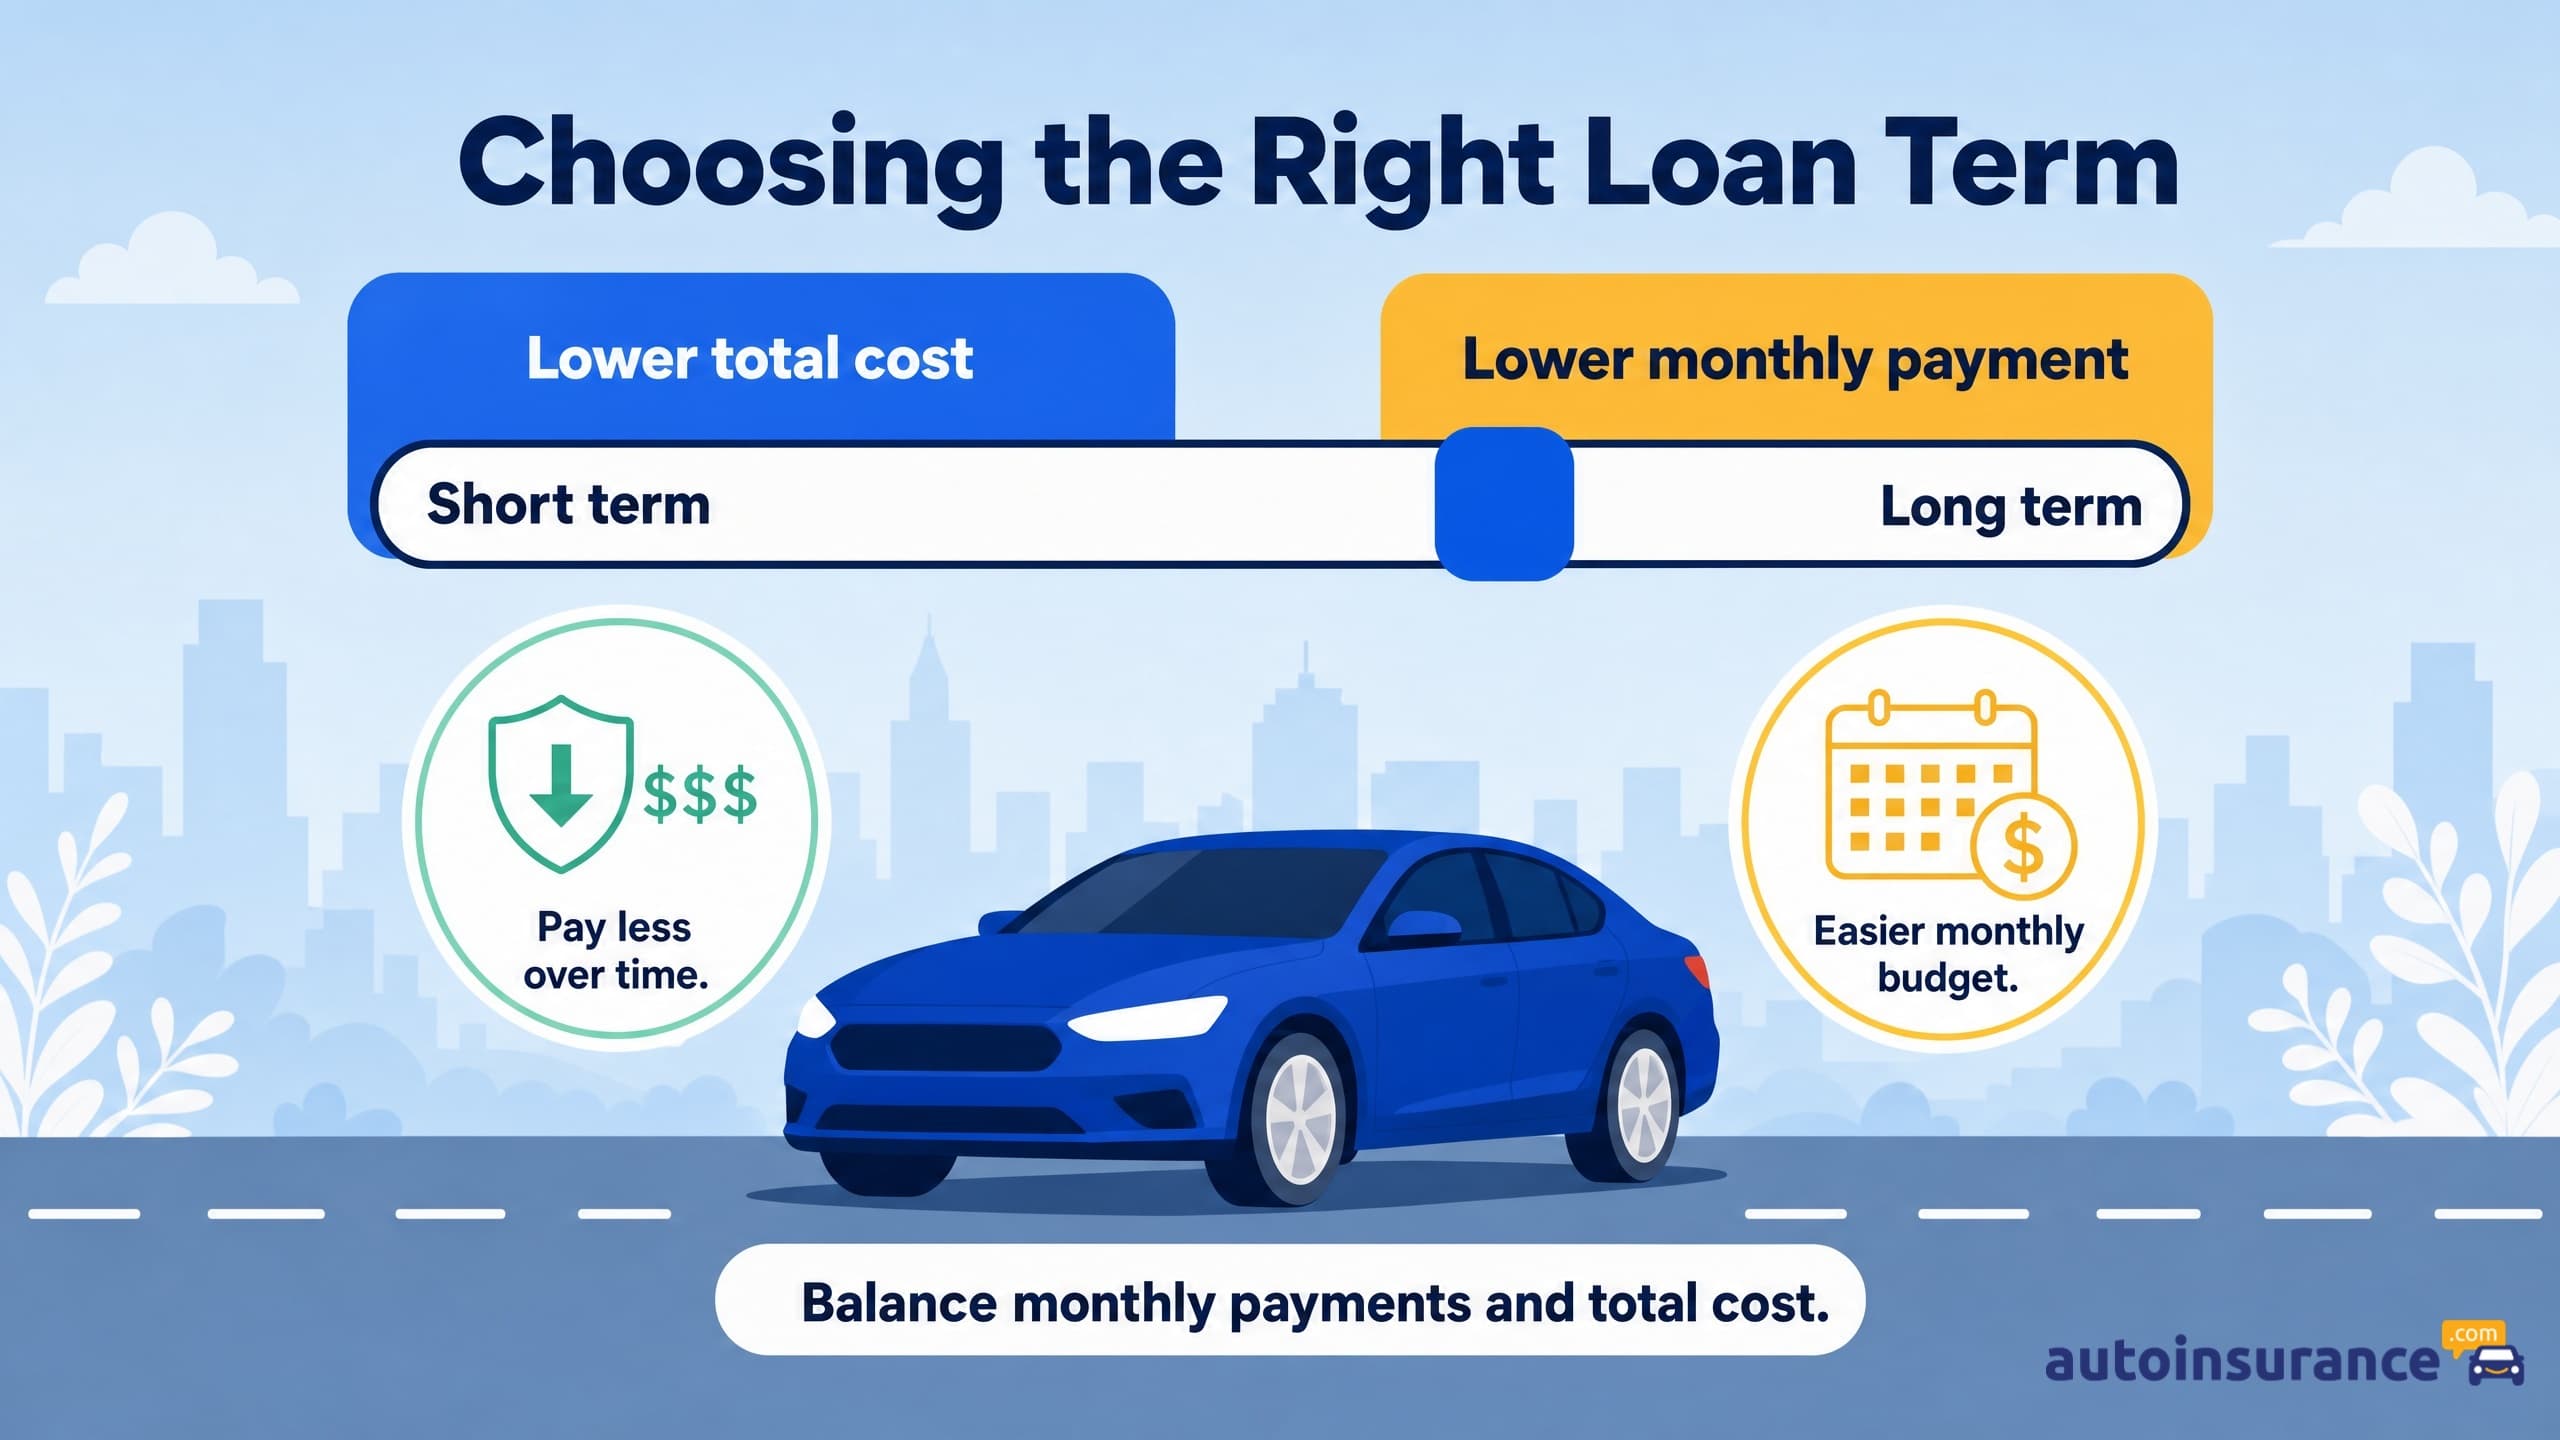
- Term length — shorter terms usually mean higher monthly payments, but less total interest paid over the life of the loan
- Discounts — some lenders offer rate discounts for autopay or existing customers
- Penalties — check for prepayment penalties or late-payment fees
- Down payment requirements
- Application fees
Get Preapproved
Before you buy, get preapproved for a loan through a traditional bank, credit union, or online lender. Most offer preapproval online or by phone.
The lender will run a soft credit check to review your credit report. This won’t affect your credit score. A hard inquiry, by contrast, happens once you formally apply for a loan and can have a small, temporary impact on your score.
We recommend getting preapproved through multiple lenders so you can compare terms before committing. Note that not every lender offers preapproval — some require a full application (and a hard inquiry) upfront.
 866-589-5339