866-589-5339




What happens if my car is declared a total loss?
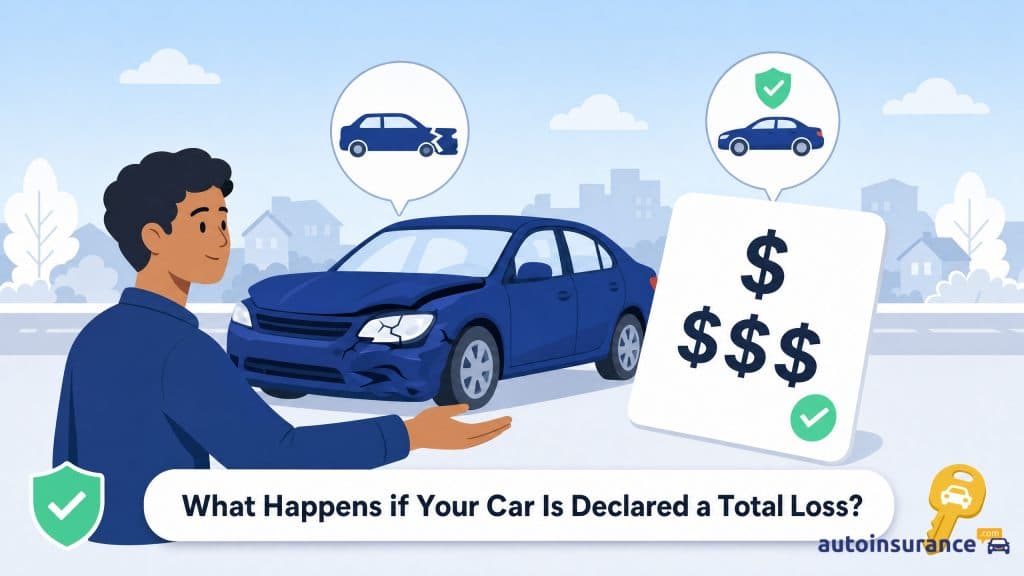
Insurers declare a total loss when car repairs cost too much versus its actual cash value, then pay out ACV, take the title, and sell it for salvage.
July 14, 2026
If you’re not driving your car for 30 days or more, you may be able to suspend or reduce coverage — but it’s important to file the proper paperwork to avoid penalties for not having insurance.
Get quotes from providers in your area

Discover rates as low as $24 /month

If you’re not driving your car for 30 days or more, you may be able to suspend or reduce coverage — but it’s important to file the proper paperwork to avoid penalties for not having insurance.
If you’re not planning to drive your car for a month or longer, you may be wondering whether you can temporarily suspend your car insurance to save money.
The short answer: sometimes — but it depends on your state’s laws and your insurance company’s policies. In many cases, what people call “suspending” insurance actually means switching to a lower level of coverage rather than fully pausing the policy.
Here’s what you need to know before making changes.
Find flexible coverage.
Compare quotes for cheap, flexible auto insurance today.
In most states, you must maintain liability insurance on any vehicle that is registered, even if you aren’t driving it. States electronically monitor insurance coverage, and a lapse can trigger fines, registration suspension, or higher premiums later.
However, you may be able to suspend or reduce coverage if:
The rules vary significantly by state, so always verify DMV requirements before canceling or reducing coverage.
Insurance companies rarely offer a true “pause” where billing stops entirely. Instead, suspension usually falls into one of three categories:
This typically involves dropping liability and collision coverage, but maintaining comprehensive coverage. This option allows you to maintain continuous insurance history while lowering your premium.
Some insurers may allow a formal suspension in limited situations, such as military deployment or extended overseas travel. This is not widely offered and often requires documentation.
You can cancel your policy entirely, but this could create a lapse in coverage and increase future premiums. You should only cancel your policy if you sell or properly de-register your vehicle, which usually requires surrendering plates or filing non-use paperwork. If you don’t and your vehicle remains registered, you can trigger DMV penalties.
If you cancel your policy, consider buying a nonowner policy. Nonowner insurance provides liability coverage if you drive or rent a car, and prevents gaps in your insurance history.
You may consider reducing coverage if:
If you’re financing or leasing your car, you generally cannot suspend coverage. Lenders require full coverage (liability, collision, and comprehensive) until the loan is paid off.
| Situation | Best Option |
|---|---|
| Storing vehicle long-term | Keep comprehensive only |
| Military deployment | Ask about insurer suspension program |
| Vehicle under repair | Reduce to storage coverage |
| Selling vehicle | Cancel after plate transfer |
| Financing or leasing | Maintain full coverage |
Lower monthly premium while the car is not in use
Avoids a full lapse in insurance history
Maintains protection against theft and weather damage (if keeping comprehensive)
Not all insurers allow suspension
Cannot suspend if financing or leasing
May require DMV paperwork
Reduced coverage means reduced protection
Frequent suspensions may affect underwriting eligibility
Some states like California and Wisconsin allow you to surrender your plates and registration if you don’t drive your car. It’s a good option for seasonal vehicles and project cars. Other states have no formal procedure for suspending registration. When in doubt, contact your DMV.
If you cancel insurance but keep your vehicle registered:
Check out our top picks for auto insurance after a coverage lapse.
If your goal is to reduce expenses, consider:
If you drive infrequently, a pay-per-mile or telematics-based policy may provide savings without risking a coverage lapse.
You may be able to suspend or reduce your car insurance if you won’t be driving for an extended period, but it depends on your state’s registration laws and your insurer’s policies.
In most cases, switching to comprehensive-only storage coverage is the safest way to lower your premium while avoiding penalties and coverage lapses.
Before canceling or suspending coverage, always confirm both your insurer’s rules and your DMV’s requirements.
Insurers declare a total loss when car repairs cost too much versus its actual cash value, then pay out ACV, take the title, and sell it for salvage.
July 14, 2026
Car insurance stays active after the policyholder’s death, with the estate handling payments until transfer or cancellation within the insurer’s grace period.
November 4, 2025
A no-claims bonus (NCB) is a reward for not filing any recent claims that can save drivers up to 30 percent on insurance premiums.
October 20, 2025
If your total assets or future earnings could be lost in a lawsuit that exceeds your auto/home liability limits, umbrella insurance may be worth purchasing.
November 6, 2025Some states and insurers allow for temporary car insurance policy pauses, but it’s uncommon. Reduced coverage is more commonly allowed: for example, switching to comprehensive-only while the vehicle is stored.
Reducing coverage (while keeping the policy active) typically does not create a lapse. However, fully canceling and restarting coverage may increase your premiums.
No. If liability coverage is removed, the vehicle cannot legally be driven. Driving without required coverage can result in severe penalties.
If the vehicle is registered, usually yes. If properly deregistered and stored on private property, liability may not be required, but comprehensive coverage is still advisable.
To reactivate your car insurance after a suspension:
Can I Temporarily Suspend My Car Insurance?. Progressive Answers. (n.d.).
https://www.progressive.com/answers/temporarily-suspend-car-insurance/